Amazon Craters As Cash Burn Explodes, Weak Guide
Earlier today we asked the question every Amazon holder has been asking all year: why does this stock never work? Tonight Amazon (AMZN) answered it with one number: -$33.5 billion.
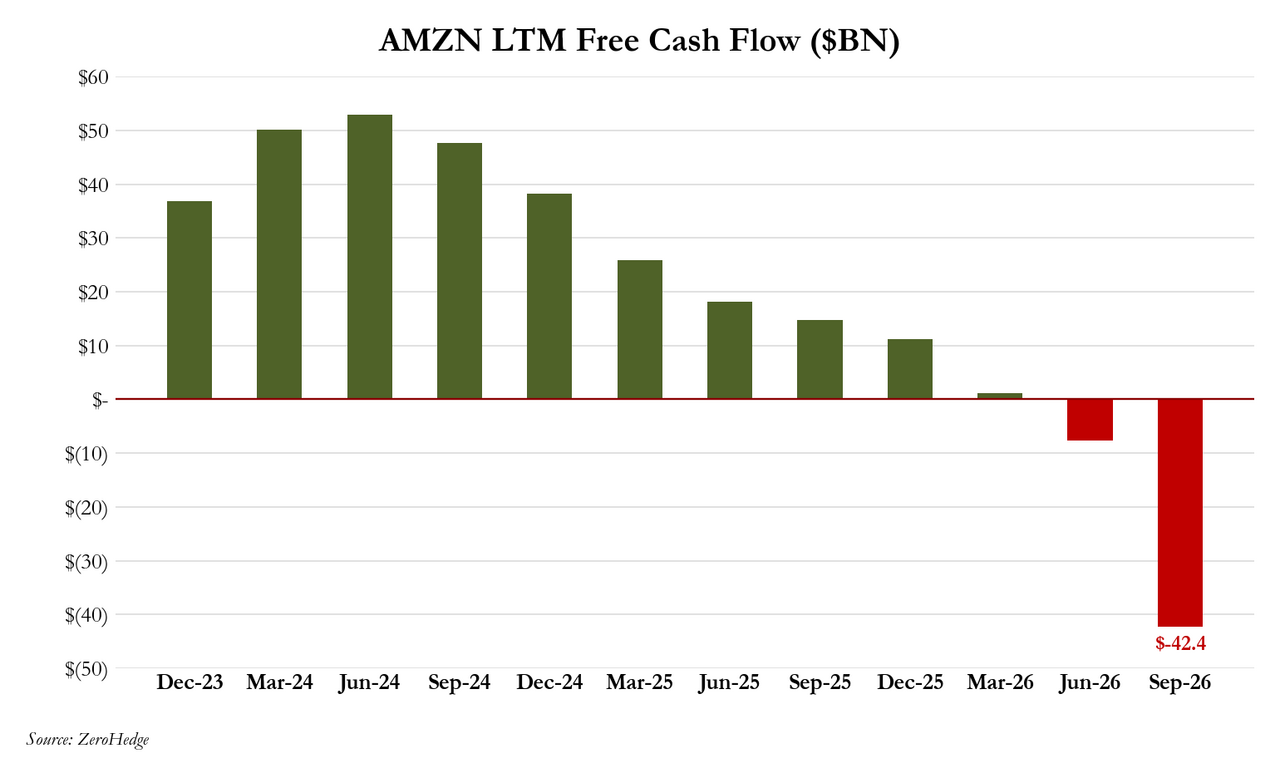
That is how much free cash flow Amazon burned in Q3 alone. Bloomberg consensus expected an outflow of $7.7 billion; Amazon came in more than four times worse, as quarterly capex exploded to $77.3 billion, up 43% from $54.2 billion in Q2. Trailing free cash flow collapsed to -$42.4 billion, from -$7.6 billion three months ago. To help pay for it, Amazon raised $48.1 billion of new long-term debt during the quarter.
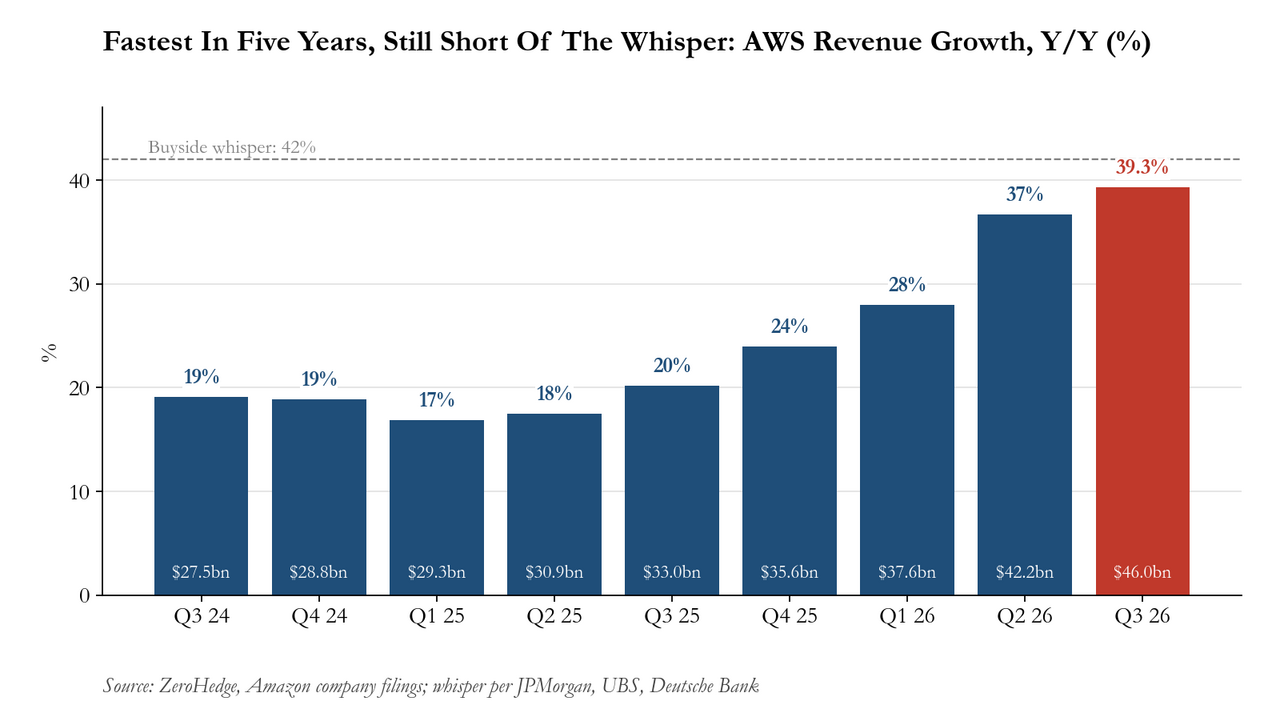
Everything else was a sideshow. AWS grew 39.3%, its fastest in nearly five years, but short of the 42% the buyside was actually looking for; operating income hit a record $28.1 billion, right on the $28 billion whisper; EPS of $1.89 missed the $1.97 consensus; and Q4 guidance came in light on both revenue and operating income.
We had a feeling:
not gonna work this time either
*AMAZON 3Q EPS $1.89, EST. $1.97— zerohedge (@zerohedge) October 29, 2026
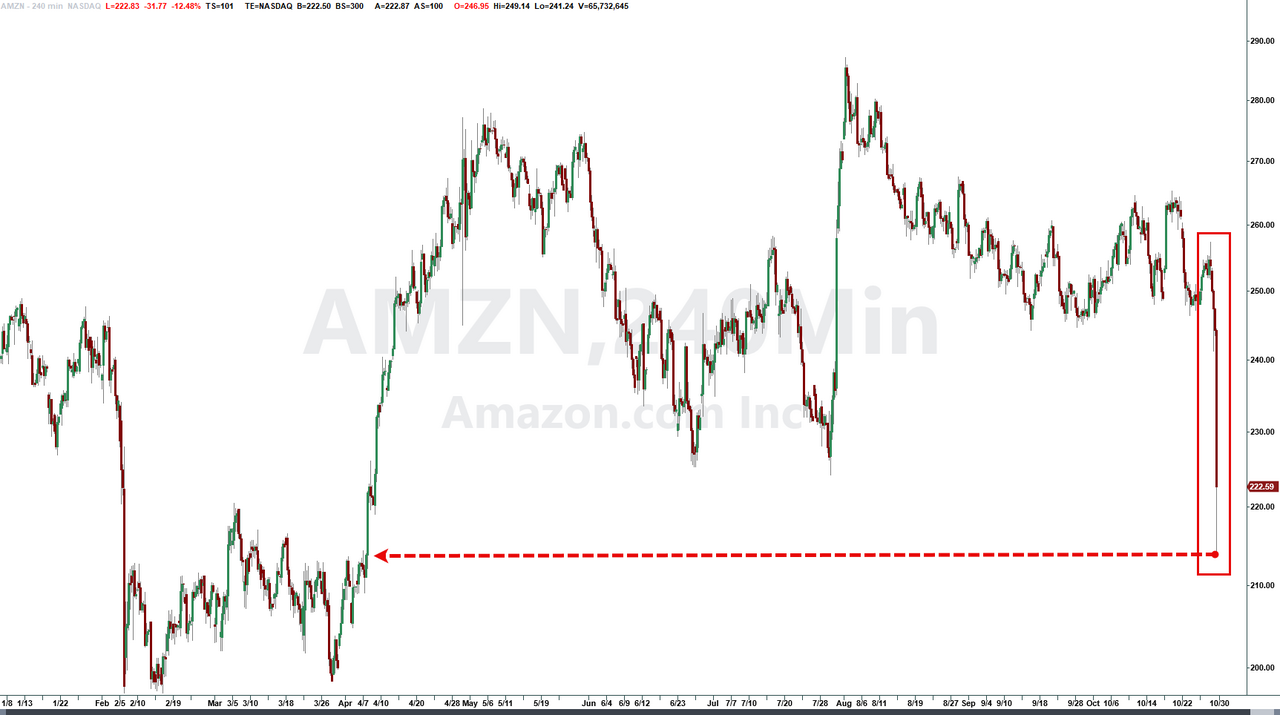
It didn't. The stock tumbled as much as 12.5% after hours to around $223 (and briefly traded down to ~$214), well beyond the 7.5% implied move, wiping out the entire post-Q2 rally and sending the stock back to levels last seen in early April.
The Number That Matters: -$33.5 Billion In One Quarter
Forget AWS for a moment. The number that matters is free cash flow, which peaked at $52.9 billion in mid-2024, turned negative in Q2 at -$7.6 billion, and is now -$42.4 billion. The math for the quarter is brutal in its simplicity: $42.4 billion of operating cash flow against $75.9 billion of net capex.
And then there is the guide. Amazon says it "continue[s] to expect" 2026 cash capex of about $220 billion. With $172 billion already spent (net) in the first nine months, that implies Q4 capex of roughly $48 billion, a 37% drop from the quarter it just reported, right as Jassy says demand still exceeds supply. Either Amazon is about to slam on the brakes in Q4, or Q3 pulled forward a chunk of spending the guide never accounted for. Either way, nobody believes 2027 will be lower: going in, the buyside was looking for $320-375 billion next year, and tonight Amazon gave no 2027 number at all.
Then there’s the guide...
For Q4, Amazon expects revenue of $240-247 billion, a midpoint of $243.5 billion vs. the $244.2 billion consensus. Operating income is guided to $28.5-33.5 billion, a midpoint of $31 billion vs. the Street’s $33 billion, and a full $1.5 billion below the $30-35 billion range the buyside was looking for, at both ends.
That’s even after the roughly $1 billion boost JPMorgan’s Schilsky expected once Amazon Leo goes live and its costs start getting capitalized.
The only line guided up was advertising, which Amazon says will rebound to high-teens growth after Q3’s 12% “timing anomaly.”
Translation: a holiday quarter with less profit than both the Street and the whisper, the same ~$220 billion capex plan, and a promise that ads will bounce back.
Who's Paying? The Bond Market
When the cash doesn't come from operations, it comes from somewhere else. Amazon's balance sheet tells you where:
- Long-term debt nearly tripled in nine months, from $65.6 billion at the end of 2025 to $173.1 billion at the end of September, thanks to $115.1 billion of new long-term borrowing year-to-date ($48.1 billion of it in Q3).
- Cash fell from $86.8 billion to $55.8 billion.
- Interest expense more than tripled to $1.7 billion in Q3, from $0.5 billion a year ago.
- "Other long-term liabilities" nearly tripled too, to $99.9 billion from $36.0 billion.
That's on top of Amazon's first-ever sterling bonds and the $8 billion Nvidia chip SPV. And all this a few hours after Microsoft, supposedly the cleanest balance sheet of the bunch, launched a $25 billion bond deal the morning after its "clean" beat. As we put it a few weeks ago, "debt becomes capex, becomes revenue, becomes EPS." Amazon just showed the first step of that chain at scale.
Last week we said the hyperscalers' off-balance sheet tally would cross $4 trillion once everyone reported.
Total Hyperscaler off balance sheet debt as of Oct 21: $3.6 trillion (with META and SPCX reporting). Expect this to cross $4 trillion when the rest report.
— zerohedge (@zerohedge) October 22, 2026
Scorecard: Street Vs. Whisper Vs. Actual
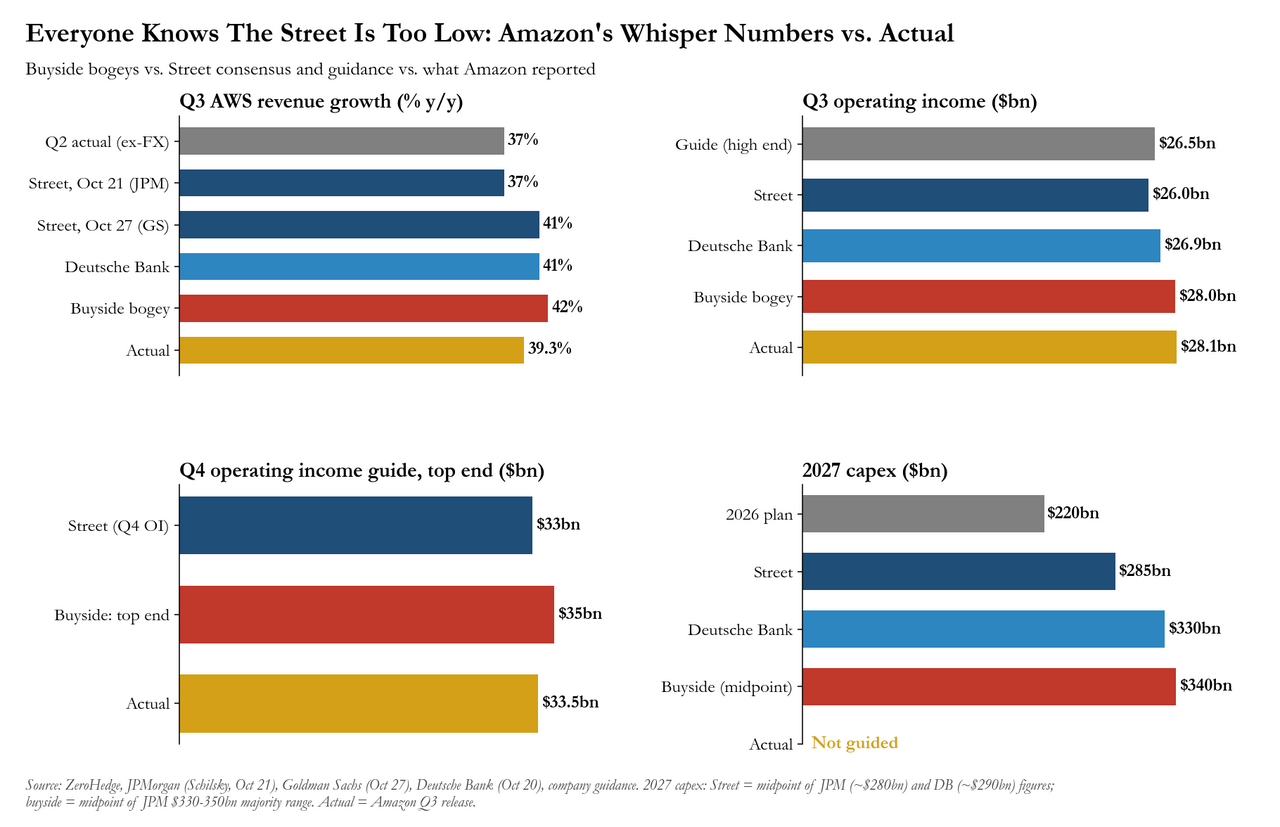
As JPMorgan's Mark Schilsky put it in his "Earnings Preview Bonanza" (available to pro subs), Street estimates were "comically low," so the real bar was the buyside whisper. Here's how Amazon did against both:
| Metric | Street | Buyside bogey | Actual |
|---|---|---|---|
| AWS revenue growth | ~37% (GS desk: ~41%) | ~42% | 39.3% |
| AWS revenue | ~$45.4B | - | $46.0B |
| AWS operating margin | ~37% | "low-40s" (UBS) | 38.7% (Q2: 39.4%) |
| Net sales | ~$202.1B (guide $197-202B) | $202-203B | $201.9B |
| Operating income | ~$26B (guide $22.5-26.5B) | ~$28B | $28.1B (record 13.9% margin) |
| EPS | $1.97 | - | $1.89 |
| Advertising growth | - | - | +12% ex-FX |
| Q4 sales guide | $244.5B | - | $240.0-247.0B |
| Q4 op income guide | $33B | top end ~$35B | $28.5-33.5B |
| Q3 capex | Q2: $54.2B | - | $77.3B gross / $75.9B net |
| Q3 free cash flow | -$7.7B (Bloomberg) | - | -$33.5B |
| LTM free cash flow | Q2: -$7.6B | - | -$42.4B |
| 2027 capex | ~$280B | $320-375B | Not guided; 2026 still ~$220B |
| After-hours move | implied ±7.5% (24Q avg realized 6.6%) | as much as -12.5% | |
The pattern is clear in the chart: Amazon cleared the Street almost everywhere and the whisper almost nowhere. AWS split the difference between the Street's 37% and the buyside's 42%, operating income essentially matched the whisper, and the Q4 guide fell short of both.
AWS: The Best Quarter In Five Years Wasn't Enough
On its own, AWS was strong: revenue rose 39.3% to $46.0 billion, a $184 billion run rate and its fastest growth in nearly five years. Jassy even handed the bulls the line they were waiting for, projecting AWS growth of "over 40%" in both 2027 and 2028. Recall that Schilsky's whole complaint going in was that the Street's 2027 AWS estimate of +35% was "waaay too low."
But the margin went the wrong way, slipping to 38.7% from 39.4% in Q2, against a buyside that wanted the low 40s. And the question we flagged in the preview, how much of the sold-out capacity actually came online given the Nvidia racks collecting dust in warehouses and Amazon walking away from Loudoun County, got no answer in the release.
Retail, Ads And The Missing Anthropic Gain
Retail was fine: North America sales rose 6% and international 8% ex-FX, roughly in line. Advertising was not: growth slowed to 12% ex-FX, which Amazon blamed on Prime Day "timing anomalies" while guiding to high-teens growth in Q4. That will feed straight into the agent debate, after Amazon blocked Meta's Muse and Deutsche warned that agent-led shopping could eat into Sponsored Products. Schilsky "guaranteed" the agent question would come up on the call, and warned that punting "will NOT go over well."
As for the EPS miss, blame the absence of an Anthropic windfall: last year's Q3 included $9.5 billion of pre-tax gains on the stake, while this year non-operating items were a $1.2 billion drag, including that tripled interest bill.
Why This Stock Never Works, Part II
Going in, Amazon was one of the most crowded longs in tech (8/10 on Goldman's TMT desk gauge, 9/10 on UBS's sentiment scale), and JPMorgan's Schilsky had the clearest diagnosis of the problem:
"AMZN has been one of the most frustrating stocks for the largest cohort of investors this year... Street estimates for 2027 AWS are too low. Comically low... As a result, investors across the ecosystem who have been trained to buy major expected KPI revisions see AMZN as an easy beat-and-raise story. But everyone knows that. It's a BIG part of the reason the stock isn't working."
Tonight Amazon delivered the AWS acceleration and even the 2027-28 growth talk, and the stock still fell 12%. Because, as we wrote in our preview this afternoon, the Q3 numbers were always going to be the easy part; the hard part was the bill. The bill came in at $77 billion of capex in one quarter, $33.5 billion of cash burn, and $48 billion of new debt. We'll allow ourselves a modest victory lap.
The stock "never works" because every dollar of AWS upside comes with more than a dollar of new spending attached. Tonight it was closer to four.
Much more in the full JPM "Earnings Preview Bonanza" and Goldman's "US eCommerce Q3'26 Preview", both available to pro subs.